The State of Outsourced Services
into Senior Living
2026 Market Report
Senior living facilities increasingly rely on outside partners to care for their residents, from primary care and behavioral health to specialty services, rehab and pharmacy, among many others. Demand is backed by one of the fastest-growing populations in the country: the 75+ cohort is projected to nearly double, from 22 million to 43 million, by 2040. With 77% to 86% of long-term care facilities already using a clinically integrated provider, outsourcing is now the default model for operators.
The fundamentals behind the sector are compelling:
- Strong Unit Economics: Senior living residents are among the highest-utilization patients in healthcare, and 79% of adults over 65 live with multiple chronic conditions. That drives meaningful revenue per resident across every service line, and best-in-class platforms run gross margins above 40%.
- Value-Based Care Upside: LTC-focused ACOs generate 6.6x the gross savings per beneficiary of other ACOs, creating a second earnings stream for facility-embedded platforms.
- Mission-Critical Partner: With 99% of nursing homes reporting difficulty recruiting clinical staff and fewer than 7,000 certified geriatricians nationwide, an embedded clinical partner has become essential to managing acuity on site.
These fundamentals are driving premium valuations, with buyers paying some of the strongest multiples in healthcare services for platforms across a range of sizes and service mixes. Deal activity reflects it: since 2021, the sector has seen 120 transactions, including 26 new sponsor platforms and 56 add-ons, with 16 closed so far in 2026. Premiums depend on organic growth, facility partner retention and diversification, a clean compliance history and a demonstrated ability to keep patients out of the hospital.
Inside the report
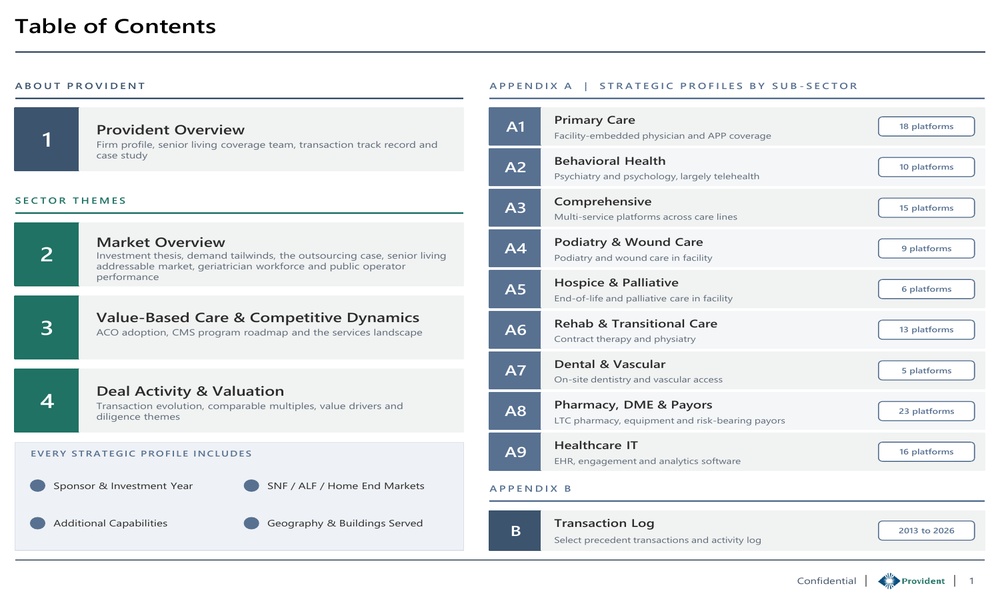
Our 50+ page report covers market dynamics, the value-based care landscape, deal activity and valuation drivers, plus profiles of 115 platforms across nine sub-sectors.